
Description
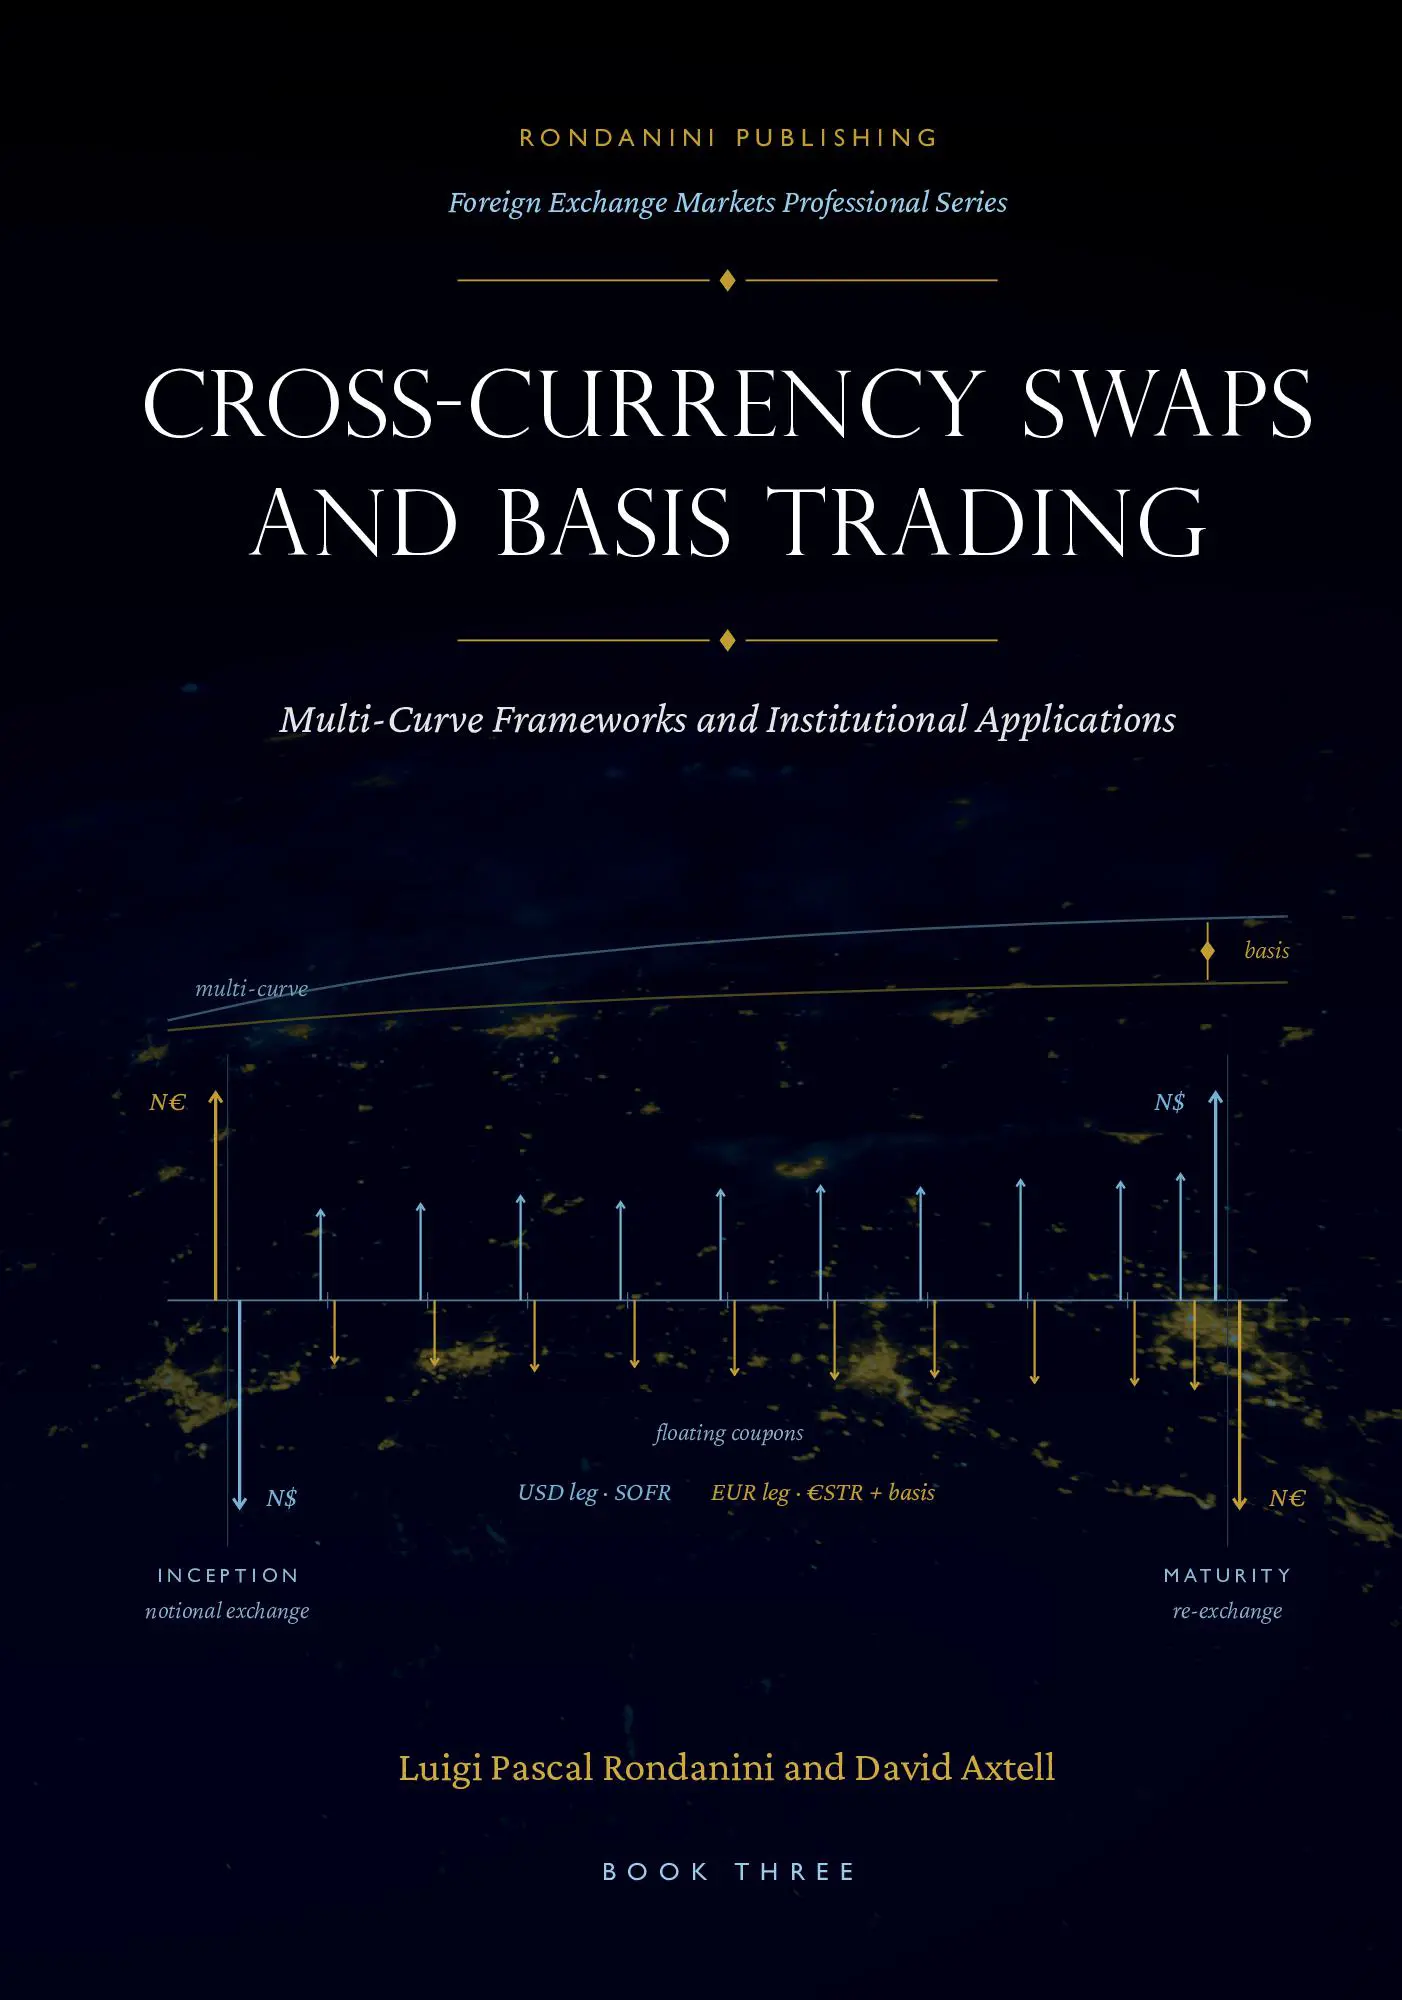
Book 3 of the Foreign Exchange Markets Professional Series by Luigi Pascal Rondanini and David Axtell. Cross-Currency Swaps and Basis Trading is a practitioner desk reference on the instruments that sit at the centre of international funding, hedging and relative-value markets: cross-currency swaps, the cross-currency basis, and the multi-curve frameworks used to value and risk-manage them on institutional desks.
The book develops how multi-curve construction works in practice – discounting, projection, tenor basis and collateralisation – and shows how those curves feed valuation, P&L explain and risk for cross-currency products. It treats the basis as a traded market, not only as a valuation residual: drivers of the spread, how desks express views, and how funding and CSA terms change the economics of a trade.
Coverage is aimed at people who price, hedge or oversee cross-currency exposures day to day: FX and rates traders and market makers; corporate and bank treasury; ALM and funding desks; market and counterparty risk; and quantitative staff supporting institutional books. Topics include curve building and calibration, notional exchange and interest legs, valuation under multi-curve and OIS discounting, basis trading and relative value, funding and liquidity effects, and institutional applications across treasury, markets and risk.
Written as a desk reference rather than a classroom textbook: structured explanations, worked context and institutional practice, in the same series voice as the volumes on FX cash products and FX options. First edition, December 2026.




Reviews
There are no reviews yet.